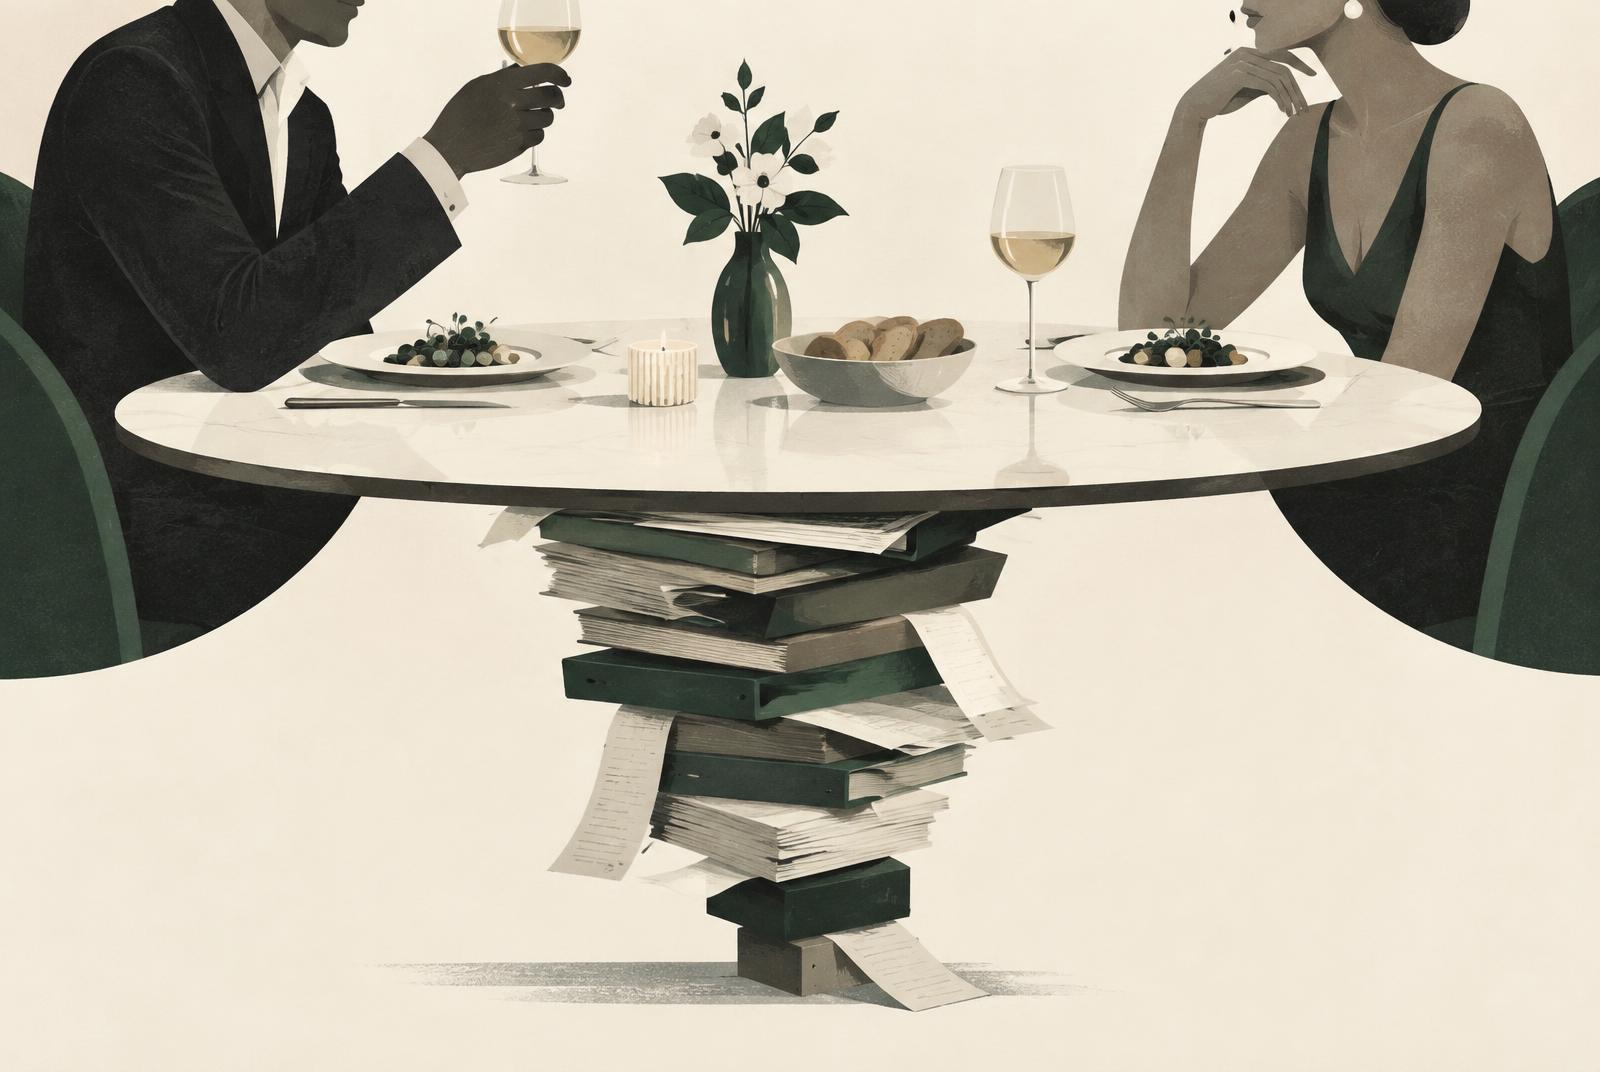
You’re good at making it look normal.
You show up. You split the check. You say yes to the birthday weekend because explaining why you can’t feels worse than figuring out how to pay for it.
Later, alone, you open the app.
Move money. Check another balance. Work out what can wait until Friday.
Nobody at dinner saw that part.
And because nobody thinks you’re struggling, the invitations and expectations keep coming.
The price of “I’m fine”
Debt doesn’t have to begin with extravagance. A repair, a gap between jobs, or helping family can start the shortfall.
But once your circumstances change, keeping your old routine can make the gap harder to close.
There’s the expense itself. Then there’s the pressure to act as though it still fits your budget.
“It’s only one dinner.”
“I’ll catch up next month.”
“They’ll think something’s wrong.”
So you keep paying for a version of your life that everyone recognizes—even when the numbers behind it have changed.
You don’t have to look like you’re in trouble to need a different plan.
Here’s the number your salary doesn’t tell you
How much is actually left after essentials, debt payments, and a realistic allowance for things that don’t happen every month?
That last part matters. Repairs, annual bills, and replacing a broken phone still count, even when they aren’t due today.
For a hypothetical household taking home $5,000, with $3,600 in essential expenses and $1,000 in debt payments, the apparent cushion is $400. Set aside $300 for irregular costs, and the margin becomes $100.
A decent paycheck. Almost no room for error.
If that feels familiar, check three things:
Your total balances: Are they falling, staying flat, or growing?
Your everyday spending: Are you borrowing again for essentials after making payments?
Your fallback: Would an ordinary unexpected bill require more debt?
The answers are more useful than whether you managed to make everything look fine this month.
A quieter way to change things
You don’t owe your friends your account balances. “That’s outside my budget right now” is enough.
But privately, you need the whole picture: what you owe, what comes in, and what you can consistently afford.
From there, compare approaches. Contacting creditors, exploring nonprofit credit counseling, and reviewing other debt-resolution options are different starting points. Ask what each would cost and what would happen to your accounts.
Debt settlement seeks agreement to pay less than you owe, but creditors may refuse. It can damage credit, involve fees, and expose you to collections or lawsuits; forgiven debt may have tax consequences. Understand those trade-offs before enrolling. Source: CFPB
Start with a question you can answer
Debt Release Program’s questionnaire begins with how much debt you have.
Its page describes the initial check as free, with no Social Security number, no credit pull, and no obligation. The information is used to help match visitors with a program in its network.
Checking is an inquiry—not a promise of savings or a decision to enroll. If a program is offered, ask about the provider, total fees, payment requirements, and possible credit impact.
You can keep saying “I’ll figure it out” after every expensive month.
Or you can start finding out what your options actually are.
Real People, Real Results
Individual experiences. Results vary.
★★★★★
“Debt Release Program felt like talking to a real person, not a call center. They walked me through every option and never pushed me into anything.”
★★★★★
“I was drowning in credit card payments. After one phone call, I had a plan I could actually afford. Two years in and I can finally see the end.”
★★★★★
“Honest, clear, and patient. They explained the trade-offs instead of giving me a sales pitch. That's what made me say yes.”